
Singapore CBD Office Market Outlook for 2026
Grade A rents, vacancy trends and what tightening supply in the core CBD means for tenants planning lease renewals over the next 18 months.
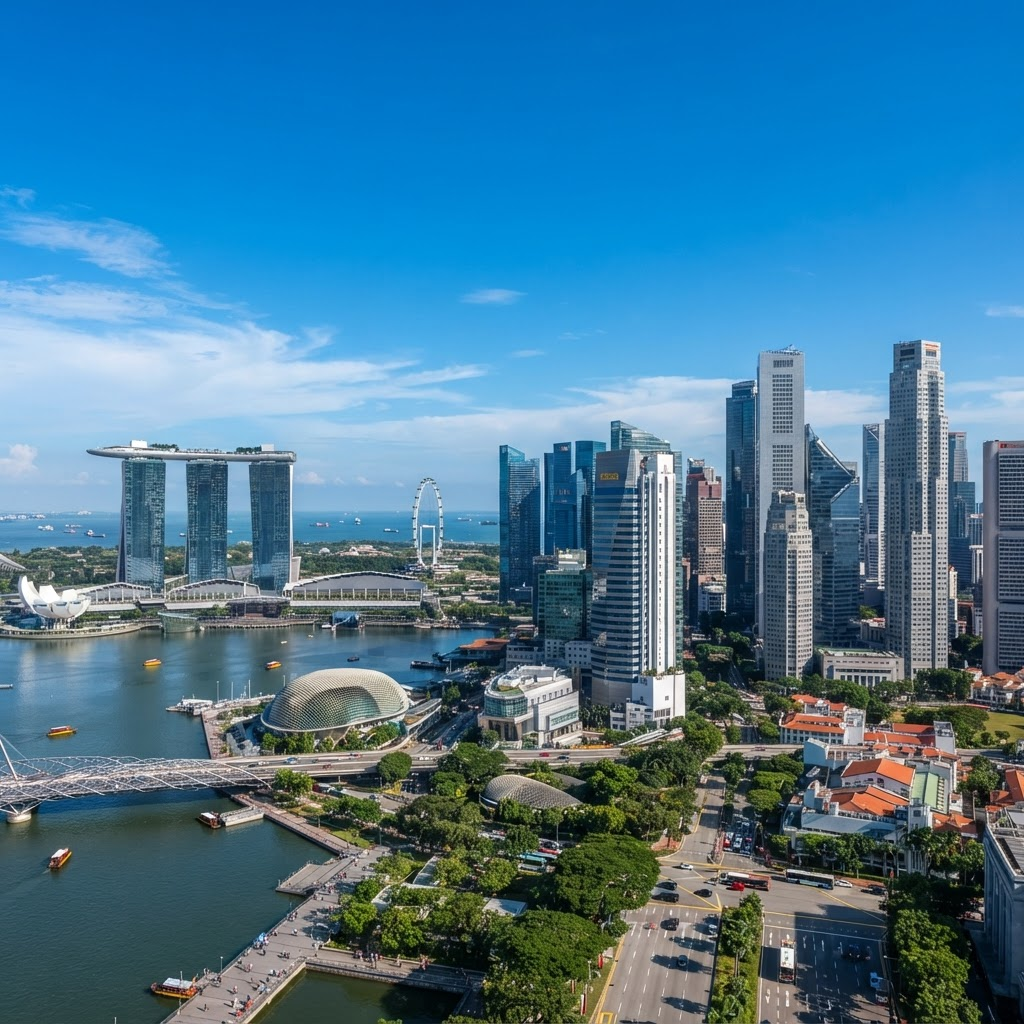
The Singapore core CBD office market enters the second half of 2026 with limited new supply and steady demand from financial services, technology and professional-services occupiers. Grade A rents have held firm through the first half of the year, and landlords of well-located, recently refurbished towers continue to command a premium over older stock.
For tenants, the practical implication is that waiting for a soft patch before renewing is an increasingly risky strategy. Renewal negotiations started nine to twelve months ahead of expiry give occupiers far more leverage, particularly where a credible relocation alternative can be documented.
Decentralised clusters such as Paya Lebar, one-north and the Jurong Lake District remain meaningfully cheaper than the core CBD, and several occupiers have used a split-office strategy — a smaller CBD presence paired with a decentralised back office — to control total occupancy cost without giving up a prime address.
Owners and investors should note that the divergence between prime and secondary stock is widening. Capital-expenditure decisions on older buildings, especially around lift modernisation, air-conditioning plants and green certification, increasingly determine whether an asset stays in the consideration set of quality tenants.
Have Questions About This Topic?
Speak with an advisor about anything covered in this article.